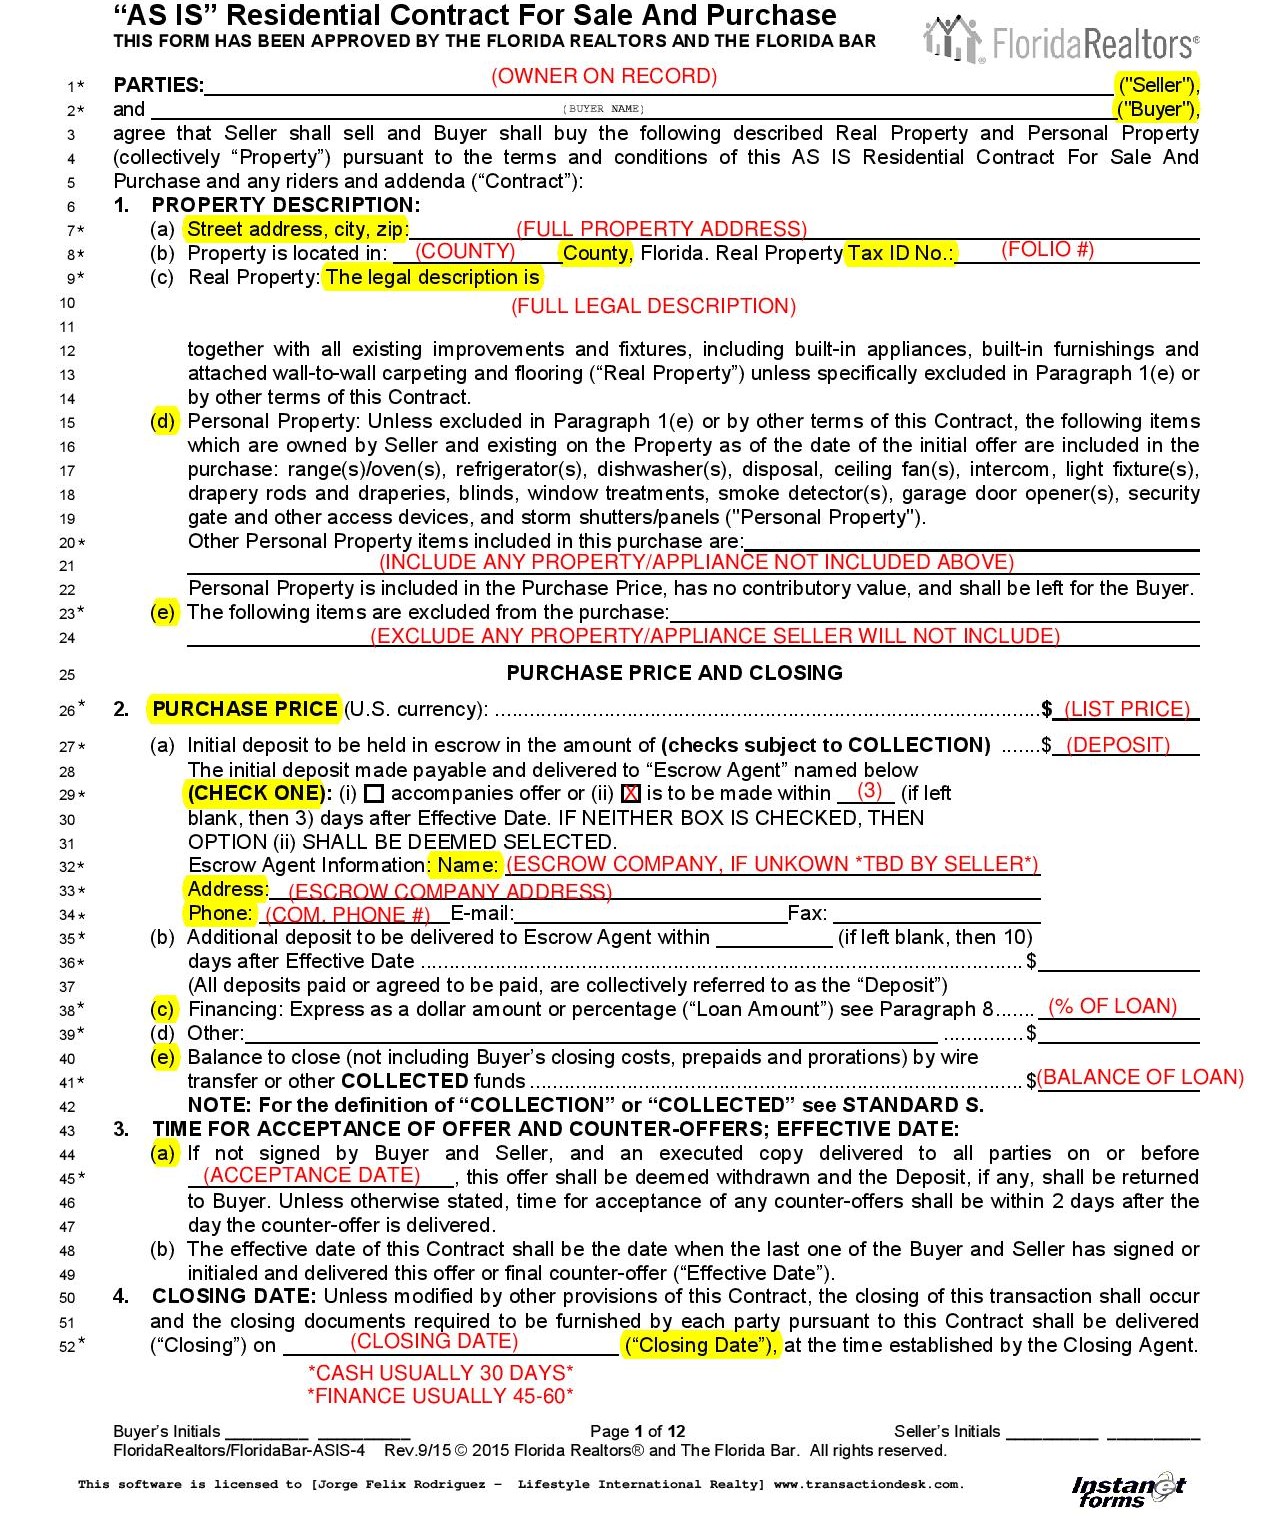
You’ve crossed your T’s and dotted your I’s and are ready to submit an offer on a house. The seller is asking for $250,000 and you think that sounds reasonable, but how can you be sure? While deciding on the aspects of your initial offer, there are several key factors that you (and your agent) should take into consideration.
What are other homes selling for in the area?
This is a monetary estimate that considers a range of factors for the property you are trying to buy, to comparable homes in the surrounding area, including:
- Age
- Size
- Construction
- Style
- Condition
A comparative market analysis can give you a clearer idea of why the price ranges in the area may differ.
How long has the property been on the market?
In cities where the market is hot, it usuallys takes less than 50 days for a home to sell. Houses that sit longer than this generally sell for less than the original asking price. Several factors can contribute to this, such as:
- High HOA fees
- High mandatory membership fees to live in a certain community
- High cost of necessary repairs to the home
It can even be due to the seller’s situation, such as a seller who’s waiting for the highest and best offer with no rushed inclination to sell.
Other key details your offer needs to include
Aside from the offer price, there are some other key details that your offer will include:
- Projected loan closing date
- Mandate that the seller will provide clear title to the property (No liens from third parties that could pose a question to ownership)
- State-required provisions or disclosures
- Details regarding the buyer’s responsibility for closing costs or other fees, and how taxes and expenses are prorated between the buyer and seller
By the time you’re ready to make an offer, you should have a good idea of what the home is worth and what you can afford to pay. Be prepared for give-and-take negotiation once you’ve made the initial offer since it’s common for this to occur when buying a home. The buyer and seller often go back and forth until they can agree on a price and contingencies.
With that in mind, be prepared to receive counteroffers which you can discuss with your real estate agent.
Contingencies
While writing the offer contract, you and your agent will go over certain escape clauses, or contingencies, that allow you to walk away from the sale without losing your escrow deposit. The most common types of contingencies are the home inspection, appraisal, financing, and title. As you go through the process, called active approval, your offer will generally be contingent on 5 things:
- Having financing at an interest rate not exceeding your budget
- Home inspection did not reveal any significant issues with the home
- Fully transparency from the seller to disclose any known issues
- No major pest infestations or damage to the property
- Seller completing an agreed upon repairs
These are a checks-and-balances system from the banks required by lenders to avoid lending any prospective buyer more than a home is worth.
Tips for putting an offer on a house
- Be proactive: Don’t wait. If you see a home you like, make an offer promptly. Homes move very quickly in a seller’s market and by the time you make a final decision the house could be gone.
- It will take time: It’s not uncommon to make offers on multiple properties before finally getting a ‘yes’. Be patient. Getting caught in a bidding war will have you spending more money than the house is worth or more than you’re comfortable spending (which is always a mistake).
- Don’t make rash decisions: Buying a home you’re not fully invested in just because you’re tired of missing out can be a grave mistake. Remember, buying a home is often a 30-year commitment. Take your time, reassess your options and make an offer based on logic rather than emotions.
Finally, keep in mind that making an offer on a home is just one step in the process.
For a complete guide on how to buy a home, read Consolidated Credit’s Guide to Homebuying for First-Time Homebuyers. And if you still have questions about making an offer on a home, a HUD-certified housing counselor can provide the information you need.